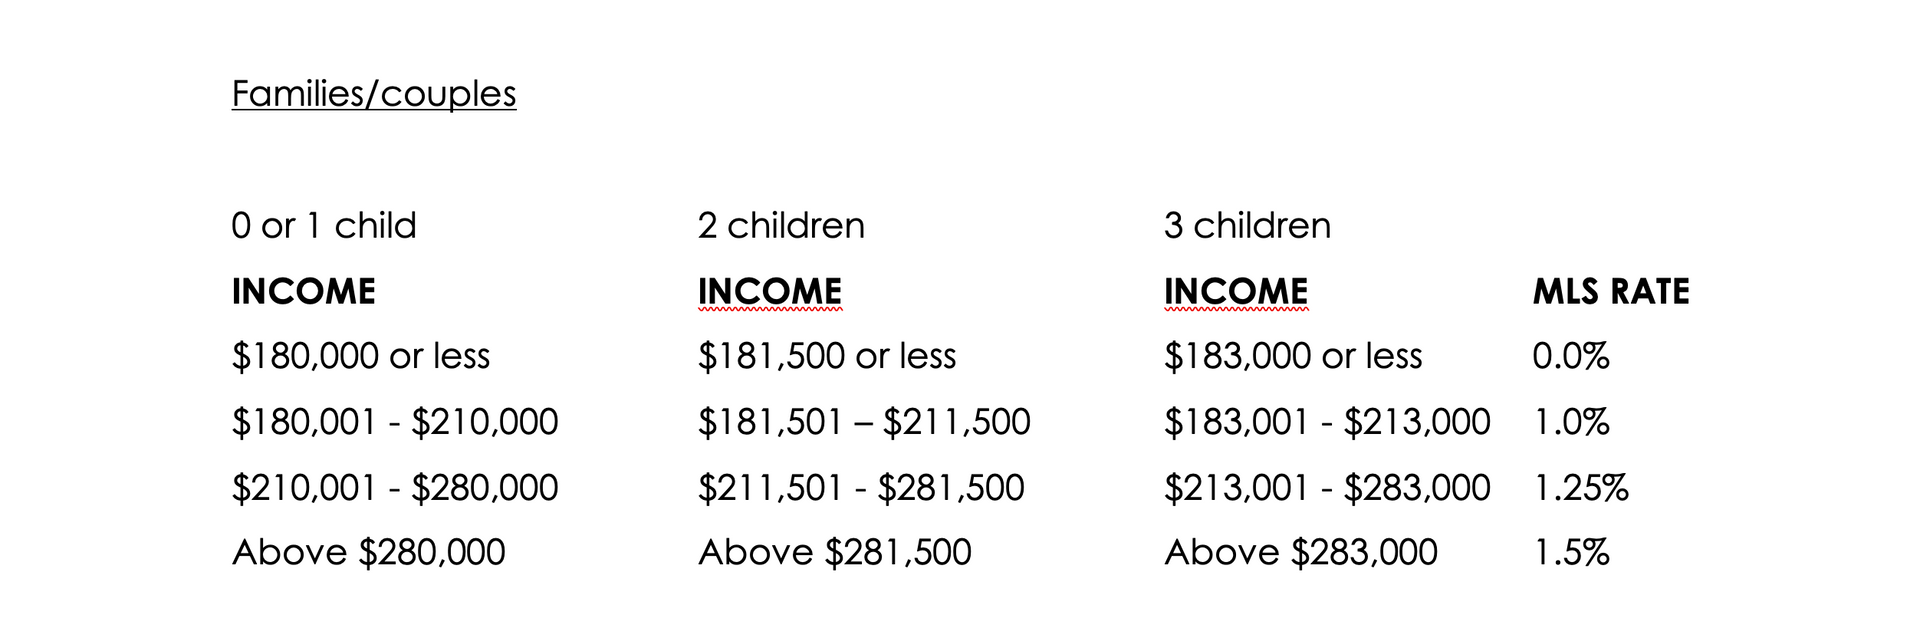What is the Medicare levy surcharge and when are you required to pay it?
The Medicare levy surcharge is designed to encourage people with higher incomes to take out private patient hospital cover. You may be liable for the Medicare levy surcharge if you exceed the relevant income threshold without an appropriate level of private health insurance.

The Medicare levy surcharge is additional to the Medicare levy. The Medicare levy is a tax Australians pay to cover the costs of our public health system (Medicare). The Medicare levy is 2% of your taxable income and automatically calculated and applied when you lodge your tax return. Typically, the Pay As You Go (PAYG) amount your employer withholds from your wages includes a portion to cover the Medicare levy. 


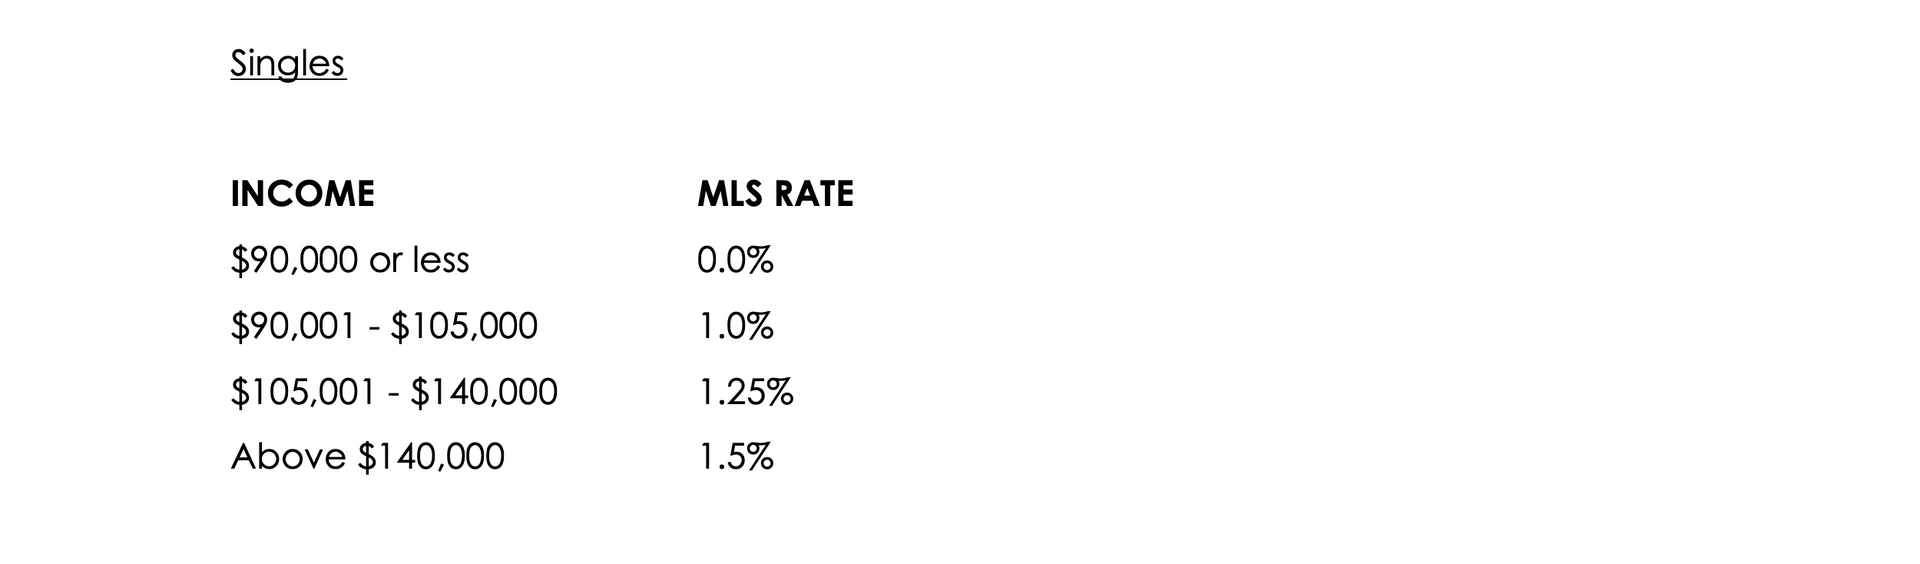
The Medicare levy surcharge is levied against an individual’s taxable income, on top of the Medicare levy, when they don’t have the appropriate level of private hospital cover. Below we’ve outlined the Medicare levy surcharge rates for the 2022-23 financial year.


Medicare levy surcharge (MLS) rates
For each additional child, the income threshold increases $1500.


While a couple’s combined income is used to determine whether the Medicare levy surcharge applies, the actual surcharge is applied individually based on each person’s taxable income. For example, if one partner earns below the low income threshold ($24,276 for 2022-23), they are not liable for the Medicare levy surcharge regardless of the combined income.


Should a taxpayer’s family circumstances change during the year (e.g., they marry or separate), the Medicare levy surcharge is calculated for each period separately, reflecting their circumstances at the time.


Paying the Medicare levy surcharge


When you lodge your tax return, if it’s determined you’re required to pay the Medicare levy surcharge, it will be combined with the Medicare levy and show as one item (Medicare levy and surcharge) on your notice of assessment.


Preparing your tax?


We know tax season can be a real headache, so we’re here to help. For accountants you can depend on for efficient and expert tax preparation, contact Ascent Accountants today. 


Need help with your accounting?

Find Out What We Do
September 14, 2026
In your 50s and thinking about retirement? Discover 10 practical strategies to boost your super and get your retirement savings on track.
September 14, 2026
Buying your first home? From deposit schemes to stamp duty concessions, here are 5 government schemes that could help you get into the market sooner.
September 14, 2026
A new way to claim work-related expenses is coming for the 2027 tax return — but there is an important catch. From 1 July 2026, eligible taxpayers can claim a standard deduction of up to $1,000 for certain work-related expenses, without having to substantiate each expense individually. Sounds simple enough. But before you assume you can claim $1,000 on top of everything else, there are a few things you need to know. The $1,000 Is the Maximum The new standard deduction is capped at $1,000. It is designed to cover certain common work-related expenses, such as work-related phone and internet, home office expenses, stationery and some travel expenses. You can't claim the $1,000 and then claim those same expenses again separately. If you have actual work-related expenses of more than $1,000, you can continue to claim your actual expenses under the existing rules, provided you meet the requirements and have the records to support them. Do I Still Need to Keep My Receipts? Yes: and this is where it is worth being organised. If you use the standard deduction, you don't need to substantiate the individual expenses covered by it. But if you think your actual work-related expenses could be more than $1,000, keeping your receipts and records throughout the year will allow you to claim your actual expenses instead. There are also some deductions that aren't covered by the standard deduction and can still be claimed separately if you are eligible. It's for Your 2027 Tax Return The new deduction applies from the 2026–27 financial year, so you won't use it for the tax return you are preparing now. It will first apply to your 2027 tax return, lodged from July 2027. Is the $1,000 a $1,000 Tax Refund? No. The $1,000 is a deduction from your taxable income. It doesn't mean you'll receive an extra $1,000 back from the ATO. The value of the deduction will depend on your individual tax circumstances. What Should You Do Now? The best thing you can do is keep track of your work-related expenses throughout the 2026–27 financial year. When it comes time to prepare your 2027 tax return, we can look at your circumstances and determine whether the standard deduction or claiming your actual expenses is likely to give you the better outcome.  At Ascent Accountants, we can help you make sense of the new rules and make sure you're claiming the deductions you're entitled to: without claiming the same expense twice!
By Nigel Parker • August 13, 2026
Late paying super under Payday Super? Learn the new deadlines, penalties, and the one step that can reduce your Administration Uplift charge.
By Nigel Parker • August 13, 2026
Received a business name or company renewal notice that looks official? Learn how to spot a fake ASIC notice before you pay.
By Nigel Parker • August 13, 2026
Negative gearing is changing from 1 July 2027. Find out what it means for established properties, new builds, and your next investment.
More Posts